Showing posts with label government debt. Show all posts

Sunday, April 29, 2012

25 Horrible Statistics About The U.S. Economy That Barack Obama Does Not Want You To Know

 
The human capacity for self-delusion truly is remarkable.  Most people out there end up believing exactly what they want to believe even when the truth is staring them right in the face.  Take the U.S. economy for example.  

Barack Obama wants to believe that his policies have worked and that the U.S. economy is improving.  So that is what he is telling the American people.  The mainstream media wants to believe that Barack Obama is a good president and that his policies make sense and so they are reporting that we are experiencing an economic recovery.  A very large segment of the U.S. population still fully supports Barack Obama and they want to believe that the economy is getting better so they are buying the propaganda that the mainstream media is feeding them.  But is the U.S. economy really improving?  The truth is that it is not.  The rate of employment among working age Americans is exactly where it was two years ago and household incomes have actually gone down while Obama has been president.  Home ownership levels and home prices continue to decline.  Meanwhile, food and gasoline continue to become even more expensive.  The percentage of Americans that are dependent on the government is at an all-time record high and the U.S. national debt has risen by more than 5 trillion dollars under Obama.  We simply have not seen the type of economic recovery that we have seen after every other economic recession since World War II.

The horrible statistics about the U.S. economy that you are about to read are not talked about much by the mainstream media.  They would rather be "positive" and "upbeat" about the direction that things are headed.

But lying to the American people is not going to help them.  If you are speeding in a car toward a 500 foot cliff, you don't need someone to cheer you on.  Instead, you need someone to slam on the brakes.

The cold, hard reality of the matter is that the U.S. economy is in far worse shape than it was four or five years ago.

We have never come close to recovering from the last recession and another one will be here soon.

The following are 25 horrible statistics about the U.S. economy that Barack Obama does not want you to know....

#1 The percentage of Americans that own homes is dropping rapidly.  According to Gallup, the current level of home ownership in the United States is the lowest that Gallup has ever measured.

#2 Home prices in the U.S. continue to fall like a rock as well.  They have declined for six months in a row and are now down a total of 35 percent from the peak of the housing bubble.  The last time that home prices in the United States were this low was back in 2002.

#3 Last year, an astounding 53 percent of all U.S. college graduates under the age of 25 were either unemployed or underemployed.

#4 Back in 2007, about 10 percent of all unemployed Americans had been out of work for 52 weeks or longer.  Today, that number is above 30 percent.

#5 When Barack Obama first became president, the number of "long-term unemployed workers" in the United States was 2.6 million.  Today, it is 5.3 million.

#6 The average duration of unemployment in the United States is about three times as long as it was back in the year 2000.

#7 Despite what the mainstream media would have us to believe, the truth is that the percentage of working age Americans that are employed is not increasing.  Back in March 2010, 58.5 percent of all working age Americans were employed.  In March 2011, 58.5 percent of all working age Americans were employed. In March 2012, 58.5 percent of all working age Americans were employed.  So how can Barack Obama and the mainstream media claim that the employment situation in the United States is getting better?  The employment rate is still essentially exactly where it was when the last recession supposedly ended.

#8 Back in 1950, more than 80 percent of all men in the United States had jobs.  Today, less than 65 percent of all men in the United States have jobs.

#9 In 1962, 28 percent of all jobs in America were manufacturing jobs.  In 2011, only 9 percent of all jobs in America were manufacturing jobs.

#10 In some areas of Detroit, Michigan you can buy a three bedroom home for just $500.

#11 According to one recent survey, approximately one-third of all Americans are not paying their bills on time at this point.

#12 Since Barack Obama entered the White House, the price of gasoline has risen by more than 100 percent.

#13 The student loan debt bubble continues to expand at a very frightening pace.  Recently it was announced that total student loan debt in the United States has passed the one trillion dollar mark.

#14 Incredibly, one out of every four jobs in the United States pays $10 an hour or less at this point.

#15 Household incomes all over the United States continue to fall.  After adjusting for inflation, median household income in America has declined by 7.8 percent since December 2007.

#16 Over the past several decades, government dependence has risen to unprecedented heights in the United States.  The following is how I described the explosive growth of social welfare benefits in one recent article....
Back in 1960, social welfare benefits made up approximately 10 percent of all salaries and wages.  In the year 2000, social welfare benefits made up approximately 21 percent of all salaries and wages.  Today, social welfare benefits make up approximately 35 percent of all salaries and wages.
#17 In November 2008, 30.8 million Americans were on food stamps.  Today, more than 46 million Americans are on food stamps.

#18 Right now, more than 25 percent of all American children are on food stamps.

#19 According to the U.S. Census Bureau, today 49 percent of all Americans live in a home that receives some form of benefits from the federal government.

#20 Over the next 75 years, Medicare is facing unfunded liabilities of more than 38 trillion dollars.  That comes to $328,404 for each and every household in the United States.

#21 During the first quarter of 2012, U.S. public debt rose by 359.1 billion dollars.  U.S. GDP only rose by 142.4 billion dollars.

#22 At this point, the U.S. national debt is rising by more than 2 million dollars every single minute.

#23 The U.S. national debt has risen by more than 5 trillion dollars since the day that Barack Obama first took office.  In a little more than 3 years Obama has added more to the national debt than the first 41 presidents combined.

#24 The Federal Reserve bought up approximately 61 percent of all government debt issued by the U.S. Treasury Department during 2011.

#25 The Federal Reserve continues to systematically destroy the value of the U.S. dollar.  Since 1970, the U.S. dollar has lost more than 83 percent of its value.
But the horrible economic statistics only tell part of the story.

In communities all over America there is a feeling that something fundamental has changed.  Businesses that have been around for generations are shutting their doors and there is a lot of fear in the air.  The following is a brief excerpt from a recent interview with Richard Yamarone, the senior economist at Bloomberg Brief....
You have to listen to what the small businesses are telling you and right now they are telling you, ‘Hey, I’m the head of a 3rd or 4th generation, 75 or 100 year old business, and I’ve got to shut the doors’ or ‘I’ve got to let people go. And if I’m hiring anybody back, it’s only on a temporary basis.’
Sometimes they do this through a hiring firm so that they can sidestep paying unemployment benefit insurance. So that’s what’s really going on at the grassroots level of the economy. Very, very, grossly different from what you’re seeing in some of these numbers coming out in earnings releases.”
All over the country, millions of hard working Americans are desperately looking for work.  They have been told that "the recession is over", but they are still finding it incredibly difficult to find anyone that will hire them.  The following example is from a recent CNN article....
Joann Cotton, a 54-year-old Columbus, Mississippi, resident, was one of those faces of poverty we met on the tour. Unemployed for three years, Joann has gone from making "$60,000 a year to less than $15,000 overnight." Her husband is disabled and dependent on medicines the couple can no longer afford. They rely on food stamps, which, Joann says, "is depressing as hell."
Receiving government aid, however, has not been as depressing as her job search. Joann says she has applied for at least 300 jobs. Even though she can barely afford gas, she drives to the interviews only to learn that the employers want to hire younger candidates at low wages.
The experiences have taken a toll: "I've aged 10 years in the three years that I've been looking for a job," Joann told us. "I want to get a job so I can just relax and exhale ... but I can't. After a while you just give up."
Meanwhile, Barack Obama and his family continue to live the high life at the expense of the U.S. taxpayer.

Even many Democrats are starting to get very upset about this.  The following is from a recent article by Paul Bedard....
Blue collar Democratic voters, stuck taking depressing “staycations” because they can’t afford gas and hotels, are resentful of the first family’s 17 lavish vacations around the world and don’t want their tax dollars paying for the Obamas’ holidays, according to a new analysis of swing voters.
It simply is not appropriate for the Obamas to be spending millions upon millions upon millions of U.S. taxpayer dollars on luxury vacations when so many Americans are deeply suffering.

But Barack Obama does not want you to know about any of this stuff.

He just wants you to buy his empty propaganda one more time so that he can continue to occupy the White House for another four years.


Friday, February 24, 2012

America's Per Capita Debt Worse Than Greece (Graph)

Think America Can't Burn Like Greece? Think Again!


Under Obama's Plan, Gross Federal Debt Alone Soars to $75,000 Per Capita in 2022

Friday, January 13, 2012

Full-Blown Civil War Erupts On Wall Street – Financial Elite Start Turning On Each Other

Finally, after trillions in fraudulent activity, trillions in bailouts, trillions in printed money, billions in political bribing and billions in bonuses, the criminal cartel members on Wall Street are beginning to get what they deserve. As the Eurozone is coming apart at the seams and as the US economy grinds to a halt, the financial elite are starting to turn on each other. The lawsuits are piling up fast. Here’s an extensive roundup:

Time to put your Big Bank shorts on! Get ready for a run… The chickens are coming home to roost… The Global Banking Cartel’s crimes are being exposed left & right…
Prepare for Shock & Awe…

Well, well… here’s your Shock & Awe:

First up, this shockingly huge $196 billion lawsuit just filed against 17 major banks on behalf of Fannie Mae and Freddie Mac. Bank of America is severely exposed in this lawsuit. As the parent company of Countrywide and Merrill Lynch they are on the hook for $57.4 billion. JP Morgan is next in the line of fire with $33 billion. And many death spiraling European banks are facing billions in losses as well. 

FHA Files a $196 Billion Lawsuit Against 17 Banks 

The Federal Housing Finance Agency (FHFA), as conservator for Fannie Mae and Freddie Mac (the Enterprises), today filed lawsuits against 17 financial institutions, certain of their officers and various unaffiliated lead underwriters. The suits allege violations of federal securities laws and common law in the sale of residential private-label mortgage-backed securities (PLS) to the Enterprises.

Complaints have been filed against the following lead defendants, in alphabetical order:

1. Ally Financial Inc. f/k/a GMAC, LLC – $6 billion
2. Bank of America Corporation – $6 billion
3. Barclays Bank PLC – $4.9 billion
4. Citigroup, Inc. – $3.5 billion
5. Countrywide Financial Corporation -$26.6 billion
6. Credit Suisse Holdings (USA), Inc. – $14.1 billion
7. Deutsche Bank AG – $14.2 billion
8. First Horizon National Corporation – $883 million
9. General Electric Company – $549 million
10. Goldman Sachs & Co. – $11.1 billion
11. HSBC North America Holdings, Inc. – $6.2 billion
12. JPMorgan Chase & Co. – $33 billion
13. Merrill Lynch & Co. / First Franklin Financial Corp. – $24.8 billion
14. Morgan Stanley – $10.6 billion
15. Nomura Holding America Inc. – $2 billion
16. The Royal Bank of Scotland Group PLC – $30.4 billion
17. Société Générale – $1.3 billion

These complaints were filed in federal or state court in New York or the federal court in Connecticut. The complaints seek damages and civil penalties under the Securities Act of 1933, similar in content to the complaint FHFA filed against UBS Americas, Inc. on July 27, 2011. In addition, each complaint seeks compensatory damages for negligent misrepresentation. Certain complaints also allege state securities law violations or common law fraud. [read full FHFA release]

You can read the suits filed against each individual bank here. For some more information read Bloomberg: BofA, JPMorgan Among 17 Banks Sued by U.S. for $196 Billion. Noticeably absent from the list of companies being sued is Wells Fargo.

And the suits just keep coming…


Saturday, October 22, 2011

D.C. Becomes America’s Richest City; Avg. Federal Employee Makes $126,000 A Year

This is but a microcosm of how our country got so broke! How in the hell does the federal government justify paying bureaucrats that much money? Stop the Insanity!
Wake Up America!!

Federal employees whose compensation averages more than $126,000 and the nation’s greatest concentration of lawyers helped Washington edge out San Jose as the wealthiest U.S. metropolitan area, government data show.


The U.S. capital has swapped top spots with Silicon Valley, according to recent Census Bureau figures, with the typical household in the Washington metro area earning $84,523 last year. The national median income for 2010 was $50,046.


The figures demonstrate how the nation’s political and financial classes are prospering as the economy struggles with unemployment above 9 percent and thousands of Americans protest in the streets against income disparity, said Kevin Zeese, director of Prosperity Agenda, a Baltimore-based advocacy group trying to narrow the divide between rich and poor.


“There’s a gap that’s isolating Washington from the reality of the rest of the country,” Zeese said. “They just get more and more out of touch.”

Article by Patriot Update

Wednesday, June 22, 2011

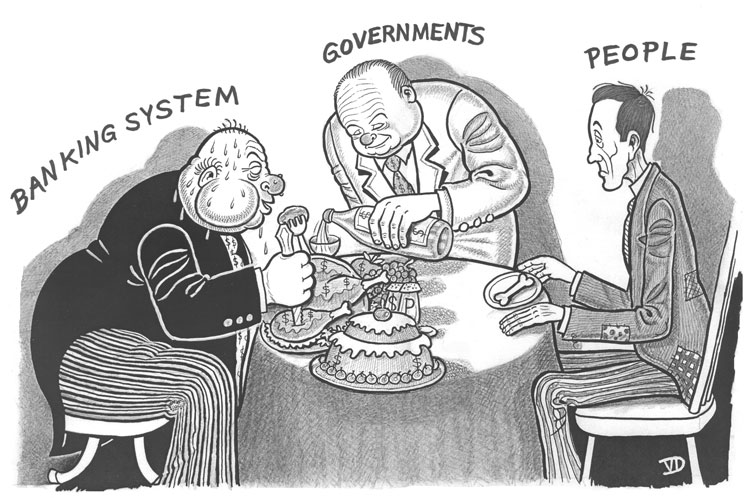
Banks Always Get Their Bailout

 
When are we going to say enough is enough? When are we going to tell our elected leaders that their job is to represent OUR interests and not those of their rich taskmasters? When??

Wake Up America!  This is YOUR land.. Take It Back!!

The fix is always in with the Big Banks.

The biggest fix was when they were declared "too big to fail," which guaranteed they'd get a taxpayer bailout, even though some of them deserved to fail, or at least deserved to be broken up. But since they had their hooks in with the politicians, they got the bailouts.

They always get the bailouts.

The latest bailout is Greece. Now, you hear a lot about a bailout for Greece, but it's not for Greece -- it's a bailout for the banks, the banks that gambled on Greek debt. Banks bought Greek debt because the Greek bonds offered really high interest rates. They offered high returns, because they were really risky bets, just like the sub-prime instruments of a few years back. And just like the sub-prime market, the Greek bond market turned out to be too good to be true. The returns were spectacular because the underlying product was lousy.

But instead of taking their losses, the banks are relying on their collection agencies -- the IMF and their friends in government -- to get their money back. The fix is in, again.

So taxpayers -- both here and in Greece -- are going to be paying off rich bankers who made lousy bets, again! It's the scam of all time, and no one seems to care. No one, except us, and, hopefully, you.

Tuesday, January 25, 2011

Fed Hides Major Accounting Change. Is This What Is Meant By "Fuzzy Math"?

Just another reason to ban the Federal Reserve! Wake up America... this (and every other) action by an independent banking cartel is bankrupting our country and that of our future generations!
  
Reuters has a very hot story out tonight on an accounting change the Fed snuck into a regular weekly report. It will move off the capital part of its balance sheet any losses the Fed may have on paper it purchased from Goldman Sachs, or anybody else for that matter. Here's Reuters via CNBC (My emphasis):
Concerns that the Federal Reserve could suffer losses on its massive bond holdings may have driven the central bank to adopt a little-noticed accounting change with huge implications: it makes insolvency much less likely.

The significant shift was tucked quietly into the Fed's weekly report on its balance sheet and
phrased in such technical terms that it was not even reported by financial media when originally announced on Jan. 6.

But the new rules have slowly begun to catch the attention of market analysts.
Many are at once surprised that the Fed can set its own guidelines, and also relieved that the remote but dangerous possibility that the world's most powerful central bank might need to ask the U.S. Treasury or its member banks for money is now more likely to be averted.
But they are averting asking the Treasury for money in the future by an accounting gimmick that will simply dump the debt off the capital part of the balance sheet, so it won't be reported as a loss, and make it a liability to the Treasury. More from Reuters:
[According to]Raymond Stone, managing director at Stone & McCarthy in Princeton, New Jersey, "An accounting methodology change at the central bank will allow the Fed to incur losses, even substantial losses, without eroding its capital."

The change essentially allows the Fed to denote losses by the various regional reserve banks that make up the Fed system as a liability to the Treasury rather than a hit to its capital. It would then simply direct future profits from Fed operations toward that liability...

 "Any future losses the Fed may incur will now show up as a negative liability as opposed to a reduction in Fed capital, thereby making a negative capital situation technically impossible," said Brian Smedley, a rates strategist at Bank of America-Merrill Lynch and a former New York Fed staffer.

"The timing of the change is not coincidental, as politicians and market participants alike have expressed concerns since the announcement (of a second round of asset buys) about the possibility of Fed 'insolvency' in a scenario where interest rates rise significantly," Smedley and his colleague Priya Misra wrote in a research note.
Bottom line: We all knew the Fed was going to have to do some kind of monkey business to deal with all the junk securities it purchased, here it is: Negative liabilities. Yes, only at your local Fed.

Note: I hasten to add this does not appear to resolve the problem of the Fed going cash flow negative as a result of having to raise interest rates on excess reserve to a point where they are higher than most of the income earning debt they hold. Expect future monkey business on this front.


Article by: Robert Wenzel, Economy Policy Journal 

Tuesday, December 14, 2010

The Scary Actual U.S. Government Debt - The US is Bankrupt!

Boston University economist Laurence Kotlikoff says U.S. government debt is not $13.5-trillion (U.S.), which is 60 per cent of current gross domestic product, as global investors and American taxpayers think, but rather 14-fold higher: $200-trillion – 840 per cent of current GDP. “Let’s get real,” Prof. Kotlikoff says. “The U.S. is bankrupt.”

Writing in the September issue of Finance and Development, a journal of the International Monetary Fund, Prof. Kotlikoff says the IMF itself has quietly confirmed that the U.S. is in terrible fiscal trouble – far worse than the Washington-based lender of last resort has previously acknowledged. “The U.S. fiscal gap is huge,” the IMF asserted in a June report. 

“Closing the fiscal gap requires a permanent annual fiscal adjustment equal to about 14 per cent of U.S. GDP.”

This sum is equal to all current U.S. federal taxes combined. The consequences of the IMF’s fiscal fix, a doubling of federal taxes in perpetuity, would be appalling – and possibly worse than appalling.

Prof. Kotlikoff says: “The IMF is saying that, to close this fiscal gap [by taxation], would require an immediate and permanent doubling of our personal income taxes, our corporate taxes and all other federal taxes.

“America’s fiscal gap is enormous – so massive that closing it appears impossible without immediate and radical reforms to its health care, tax and Social Security systems – as well as military and other discretionary spending cuts.”

He cites earlier calculations by the Congressional Budget Office (CBO) that concluded that the United States would need to increase tax revenue by 12 percentage points of GDP to bring revenue into line with spending commitments. 

But the CBO calculations assumed that the growth of government programs (including Medicare) would be cut by one-third in the short term and by two-thirds in the long term.
This assumption, Prof. Kotlikoff notes, is politically implausible – if not politically impossible.

One way or another, the fiscal gap must be closed. If not, the country’s spending will forever exceed its revenue growth, and no one’s real debt can increase faster than his real income forever.

Prof. Kotlikoff uses “fiscal gap,” not the accumulation of deficits, to define public debt. The fiscal gap is the difference between a government’s projected revenue (expressed in today’s dollar value) and its projected spending (also expressed in today’s dollar value). By this measure, the United States is in worse shape than Greece.

Prof. Kotlikoff is a noted economist. He is a research associate at the U.S. National Bureau of Economic Research. He is a former senior economist with then-president Ronald Reagan’s Council of Economic Advisers. He has served as a consultant with governments around the world. He is the author (or co-author) of 14 books: Jimmy Stewart Is Dead (2010), his most recent book, explains his recommendations for reform.

He says the U.S. cannot end its fiscal crisis by increasing taxes. He opposes further stimulus spending because it will simply increase the debt. But he does suggest reforms that would help – most of which would require a significant withering away of the state. He proposes that the government give every person an annual voucher for health care, provided that the total cost not exceed 10 per cent of GDP. (U.S. health care now consumes 16 per cent of GDP.) He suggests the replacement of all current federal taxes with a single consumption tax of 18 per cent. He calls for government-sponsored personal retirement accounts, with the government making contributions only for the poor, the unemployed and people with disabilities.

Without drastic reform, Prof. Kotlikoff says, the only alternative would be a massive printing of money by the U.S. Treasury – and hyperinflation.

As former president Bill Clinton once prematurely said, the era of big government is over. In the coming years, the U.S. will almost certainly be compelled to deconstruct its welfare state.

Prof. Kotlikoff doesn’t trust government accounting, or government regulation. The official vocabulary (deficit, debt, transfer payment, tax, borrowing), he says, is vulnerable to official manipulation and off-the-books deceit. He calls it “Enron accounting.” He also calls it a lie. Here is an economist who speaks plainly, as the legendary straight-shooting film star Jimmy Stewart did for an earlier generation.

But Prof. Kotlikoff’s economic genre isn’t the Western. It’s the horror story – “and scarier,” one reviewer of his book suggests, than Stephen King.

Article by Neil Reynolds, The Globe and Mail